Professional indemnity insurance
Page reviewed on 11 September 2026 Written by an FSMA-registered broker.
It pays for the damage your work causes a third party: faulty advice, a wrongly dimensioned drawing, a badly scoped file. Without it, the bill is yours.
-
What it coversDamage your work causes a third party
-
CompulsoryYes for regulated professions, strongly advised otherwise
-
Watch out forRetroactive cover and run-off cover
-
Our rolePutting the relevant insurers in competition and checking the exclusions
What is professional indemnity insurance?
Professional indemnity insurance covers the damage you cause unintentionally to a third party in the course of your work. What makes it distinctive: here the damage arises from your professional service, not from a physical accident. A wrongly dimensioned drawing, mistaken tax advice, a line of code that loses data, a missed diagnosis: all situations where your liability can be engaged, sometimes years after the event.
Without insurance, it is your assets, business and often personal, that answer the claim. With professional indemnity cover, the insurer handles the claim, defends you against the covered claim and pays the compensation due, within the limits of the policy.
Note: that defence is limited to the covered dispute. To fund your own steps, recover your costs, bring criminal proceedings or sue, you need extended legal expenses cover, distinct from professional indemnity.
Professional indemnity or public liability: do not confuse them
Many self-employed people think they are covered because they have “some liability cover”. In reality they often have only half of it.
Professional indemnity
Covers the faults committed in your work : faulty advice, a wrong calculation, an omission, culpable delay, a breach of obligation. The damage is most often financial, a loss suffered by the client. It is the breach of what you owed per policy.
Public liability
Covers the property damage and bodily injury caused to third parties during your activity, outside the performance of the contract: a client injured on your premises, damage caused at theirs. It also coverspost-delivery liability and goods in your care.
Depending on your trade you need one, the other, or both. A consultant: mainly professional indemnity. A tradesperson who travels: both. Public liability, post-delivery liability, goods in your care and ten-year structural liability have their own page, everything about public liability. This is exactly the kind of trade-off where a broker stops you paying for nothing, or discovering a gap on the day of the claim.
Your turnover says nothing about your risk
Three reconstructed cases: the one who invoices the most is not the one facing the largest claim. What determines the stakes is the nature of the work, not the volume of business.
- Annual turnover
- Amount claimed by the client
-
IT consultant, working alone an update fails, the client's workshop is down for 9 days95 000 €155 000 €
-
Freelance graphic designer a print run to recall and image rights not cleared60 000 €120 000 €
-
Engineering consultancy, 4 people a wrongly dimensioned drawing, a wall to knock down again320 000 €38 000 €
What limit for my activity?
Slide your turnover: it is the starting point of the conversation, not the answer.
What weighs most is not your turnover, it is the nature of your work. Two self-employed people with the same turnover can need limits that differ by a factor of twenty. The specifics of the trade, the contracts signed and the region where you work change the required limit considerably: this is a conversation to have with your broker.
Indicative, not contractually binding.
A file that halts a client's production already exceeds this level: we look at your framework contracts.
Get a quote for my activity →Covered, or not covered
We show you both columns before you sign. It is the only way not to discover an exclusion on the day of the claim.
Covered
- Error, omission, negligenceA professional fault that causes your client a financial loss.
- Bodily injury to a third partyA visitor or client injured in the course of your work.
- Property damage at the client'sWhat you damage while working, including on site.
- Defence costs and loss adjustmentThe insurer takes on the defence of your interests in the event of a claim.
- SubcontractorsOptional extension for the liability of those working for you.
Excludedded
- Deliberate actsNo policy covers damage caused deliberately.
- Your own propertyYour equipment and premises come under other policies.
- Redoing defective workRedoing the work stays at your expense: it is the third party's loss that is covered.
- Fines and penaltiesAdministrative or criminal penalties are never insurable.
- Undisclosed past eventsAn event you already knew about when taking out the policy falls outside cover.
Limits by activity
In professional indemnity there are no three universal packages: the limit depends on the trade. Here are the orders of magnitude we come across.
-
Graphic design, creativeImage rights, print recall, campaign delay.125 k€250 k€1 M€
-
IT freelancer, soloThe loss comes from the client's business interruption.125 k€250 k€1 M€
-
Interim managerBinding decisions taken on the client's behalf.250 k€500 k€1,5 M€
-
Engineer, consultancyDimensioning error, work to be redone.500 k€1,5 M€3 M€
-
Medical professionBodily injury: the limit is of a different order.not applicable5 M€€5M and above
- Limits per claim, indicative orders of magnitude: they vary by insurer, by the contracts signed with your clients and by claims history.
- Excesses are also indicative and depend on many criteria: from a few hundred euros to several thousand, depending on the activity and the insurer.
- These amounts concern professional indemnity. Public liability, often taken out alongside, follows a different logic and different limits.
A wrongly dimensioned drawing, a wall to knock down again: 38 000 € at the client's.
This is not gross misconduct, it is a professional error. With professional indemnity cover, the insurer pays and takes on the loss adjustment. Without it, it comes out of your cash flow.
-
01
The client claims
You receive a claim. You call us before replying.
-
02
We assess the file
We check the cover, the limit, the excess and the date of the events.
-
03
The loss adjustment
The insurer appoints a loss adjuster. We follow the file and translate the findings for you.
-
04
The settlement
The third party is compensated, your defence costs are covered.
How much does professional indemnity cost?
There is no single price: the premium is built on your real risk profile. The main levers:
As an order of magnitude, for €250,000 of cover and a one-person business, professional indemnity in Belgium ranges from €250 a year for a low-risk profile to €2,500 a year for the most exposed activities.
-
Designer, consultant €250 to €800
-
Manager, director €450 to €950
-
Accountant, tax adviser €600 to €1,200
-
Architect, engineer €950 to €2,500
Scale from €0 to €2,500 per year. Actual amounts depend on turnover, headcount, subcontracting, limits and insurer. Ranges to be confirmed against market rates.
The timeline of a claim
Our timing commitments, from the first call to settlement.
Compulsory for whom?
-
CompulsoryArchitectsTen-year structural cover and professional indemnity required by law.
-
CompulsoryMedical professionsDoctors, physiotherapists, nurses, dentists.
-
CompulsoryAccountants & tax advisersRequired by the ITAA for accreditation.
-
CompulsoryBuilding contractorsTen-year liability on residential works.
-
Strongly advisedConsultants & ITThe financial loss quickly exceeds the turnover.
-
Strongly advisedAgencies & marketingImage rights, delays, faulty campaigns.
-
Strongly advisedFood tradesFood poisoning, hygiene, delivery.
-
Strongly advisedHome servicesYou work at the client's, and so on their property.
What we are asked most often
Your case is not here? Ask us, we answer within 48 hours.
Ask my question →-
Professional indemnity or public liability: what is the difference?
−Public liability covers damage linked to your presence and your equipment (a client slipping on your premises, a ladder falling on a car). Professional indemnity covers the consequences of the work itself: a miscalculation, bad advice, a culpable delay. Many activities need both.
-
Is it compulsory for my activity?
+ -
How much does it cost?
+ -
Which limit should you choose?
+ -
I am switching insurer: am I covered for the past?
+ -
What if the claim arrives after the policy ends?
+
Four offices, one number
We meet at the office or come to you. One contact for all four addresses.
+32 83 23 17 23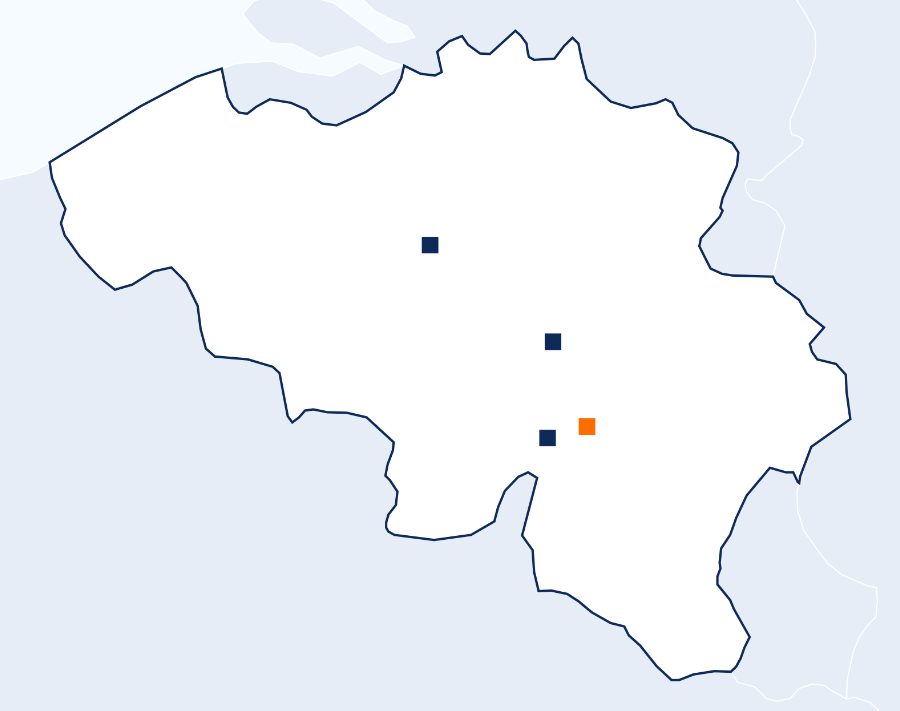 Brussels
Eghezée
Ciney
Dinant
-
BrusselsPlace de la Vieille Halle aux Blés 47
1000 Brussels -
EghezéeRoute de Cognelée 13
5310 Waret-la-Chaussée -
CineyRue des Stations 48
5590 Ciney -
DinantRue Adolphe Sax 71
5500 Dinant